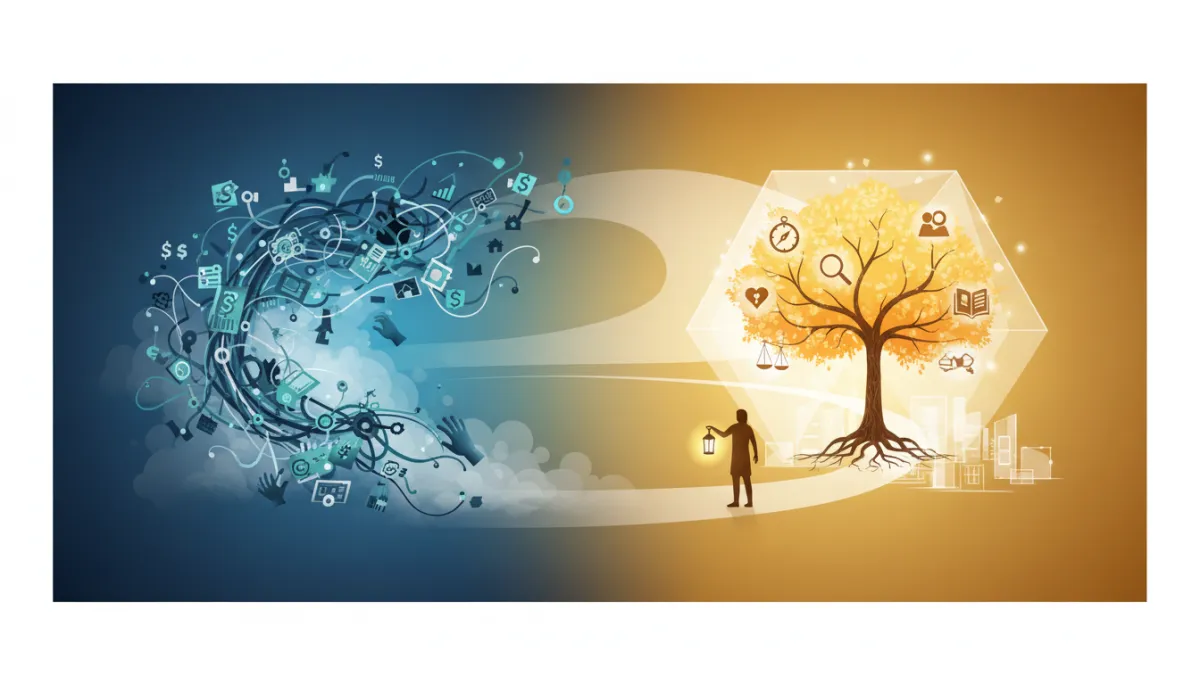
Why Financial Decisions Should Be Guided by Principles, Not Products
Financial Education, Stewardship, Wealth Design
Why Financial Decisions Should Be Guided by Principles, Not Products
When was the last time you made a financial decision because of a principle you believed in—rather than a product someone put in front of you?
Products First, Purpose Later: Why So Many People Start in the Wrong Place
Walk into almost any bank, brokerage office, or insurance seminar, and you will notice a pattern: the conversation usually starts with a product. A new account. A policy. A fund. A strategy with a catchy name. Very rarely does it start with a clear exploration of the person’s principles, purpose, or long-term design for their life and wealth.
There are reasons this happens. Products are easier to advertise than principles. They come with brochures, bullet points, and bonus offers. They can be compared on rates and returns. They create urgency: “This promotion ends Friday.” Principles, on the other hand, require reflection. They ask for honesty, patience, and uncomfortable questions like, “What am I really trying to build, and why?”
Imagine walking into a hardware store and buying the most expensive tool set because the salesperson says it’s “the best,” without knowing what project you’re working on. That is how many people approach life insurance, business entities, retirement accounts, banking, real estate, and investments. They collect tools without a blueprint. Then they wonder why the structure of their financial life feels unstable or mismatched to their actual goals.
At BDE Wealth, we see this pattern repeatedly: well-intentioned people, often responsible and hardworking, end up with a drawer full of disconnected financial tools. Not because they are careless, but because the system around them teaches “shopping” before it teaches “stewardship.” The result? Confusion, regret, and sometimes costly mistakes that could have been avoided with a different starting point: principles before products.
Reflective Question: If you looked at your current mix of accounts, policies, and investments, could you clearly explain what principle each one is serving?
Practical Lesson: Before you explore any new financial product, pause and write one sentence that begins with: “The principle I want to honor with this decision is…” Let that statement guide the rest of the conversation.
Principles vs. Products: The Foundation and the Tools
A simple analogy can clarify the difference: Principles are the laws of gravity; products are the ladders and scaffolding. Gravity doesn’t change because you bought a new ladder. In the same way, sound financial principles do not change because a new product hits the market or a new headline appears on your news feed. Principles are the underlying truths about how money, risk, time, and human behavior interact. Products are tools that can either respect those truths or ignore them.
Consider a few examples of principles:
Stewardship: I am responsible for managing resources with wisdom, not just maximizing short-term gain.
Liquidity: I need access to cash for unexpected events so I am not forced into desperate choices.
Alignment: My financial structures should match how I actually live, earn, and give—not someone else’s lifestyle or marketing story.
Products, by contrast, are specific vehicles: a certain type of life insurance policy, a particular retirement account, a specific business entity, a mortgage structure, a mutual fund, a rental property. They are the how, not the why. When you confuse the two, you end up forcing your life to fit the tool instead of choosing tools that fit your life and values.
Picture a family who values flexibility, generosity, and time freedom. If they begin with principles, they might say: “We want our money systems to give us the ability to adapt, support causes we care about, and spend time with our children.” Only then do they evaluate products life insurance, entities, banking setups, investments through that lens. The question shifts from “Is this product good?” to “Does this product help us live out our principles?”
Reflective Question: If all your current financial products disappeared tomorrow, which principles would you still want guiding your decisions?
Practical Lesson: Make a two-column list. On the left, write your top five financial principles (e.g., stewardship, liquidity, simplicity, legacy, generosity). On the right, list each major product you own. Draw lines from each product to the principle it is meant to serve. If you struggle to connect them, that’s a signal to review your design.
How Principles Lead to Better Financial Decisions
When you lead with principles, you change the decision-making process from the inside out. Instead of asking, “What’s the hottest investment?” or “Which policy has the highest return?” you ask, “What am I trying to protect, build, or express?” That shift alone can save years of frustration and thousands of dollars in misaligned decisions.
Consider life insurance. A product-first approach sounds like this: “My friend bought this type of policy; should I get the same?” A principle-first approach sounds like: “I believe in the principle of protection and provision. If something happens to me, I want my family to have time, options, and stability. What tools can support that principle given our situation?” The conversation becomes calmer, more thoughtful, and more aligned with real-life needs, not peer pressure or sales scripts.
The same holds for business entities. Many entrepreneurs rush to form an LLC or corporation because they heard it is “what serious business owners do.” But the principle might be: “I want to separate my personal and business risk, build a structure that can grow, and treat my business like a real enterprise.” Once that principle is clear, the choice of entity, banking setup, and documentation becomes part of a larger design, not a random checkbox.
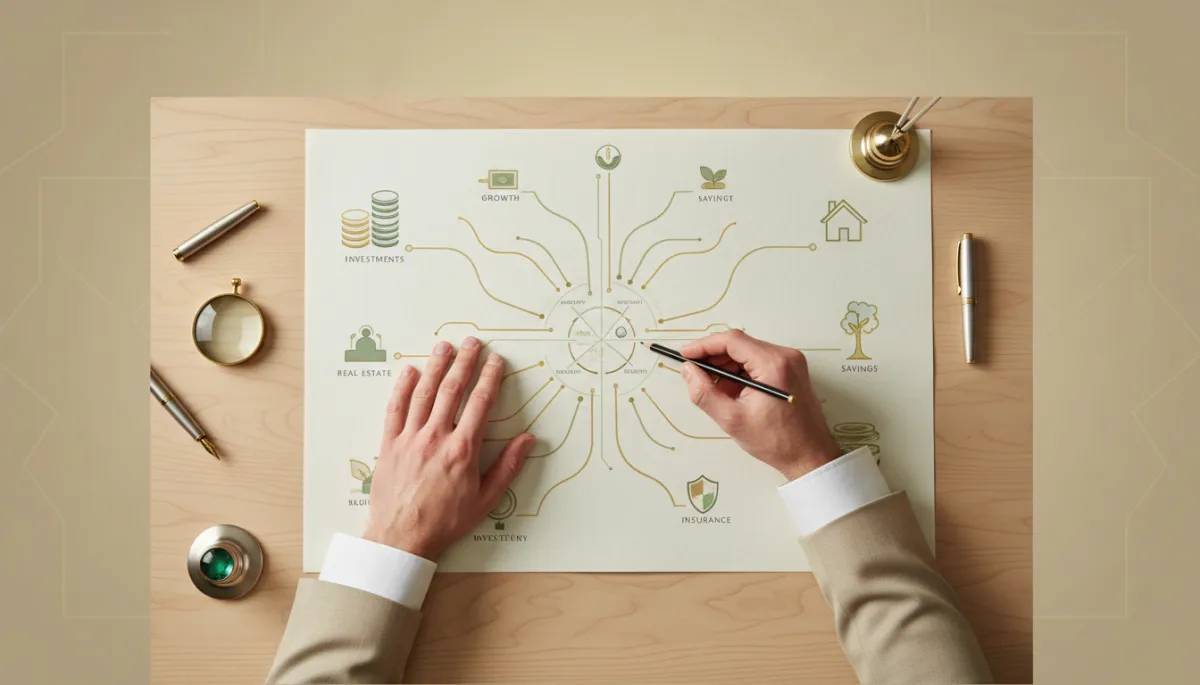
-toned overhead view of a person sketching a financial blueprint with principles written in the...
Clear principles act as a blueprint, turning scattered products into an intentional financial system.
When principles come first, several things happen:
You say “no” more easily to products that don’t fit your design, even if they sound impressive.
You feel less urgency to chase trends because your decisions are anchored to long-term values.
You evaluate advice more clearly, asking, “Does this respect my principles of stewardship, sovereignty, and intentional design?”
Reflective Question: Think of a past financial decision you regret. If you had started with principles instead of products, how might that decision have changed?
Practical Lesson: Before making your next financial move, write down three principles you refuse to violate (for example: “I will not put my family in a position where one event can wipe us out,” or “I will not commit to something I don’t understand”). Use these as your filter.
No Financial Product Is Universally “Good” or “Bad”
One of the most damaging myths in personal finance is the idea that certain products are always good or always bad. You’ve probably heard statements like, “All debt is bad,” “Real estate is the best investment,” or “That type of life insurance is a scam.” These blanket judgments ignore context, principles, and purpose. They treat tools as if they carry moral weight on their own, rather than being neutral instruments in the hands of a steward.
Think about a hammer. In the right hands, with a clear blueprint, a hammer helps build a home. In the wrong hands, or with no plan, it can cause damage. The hammer itself is not good or bad; its value depends on how and why it is used. Financial products work the same way. A business line of credit can be a lifeline for a seasonal company that manages cash flow responsibly or a trap for someone funding a lifestyle they cannot afford. A rental property can be a powerful wealth-building asset for a patient, educated investor or a stressful burden for someone who never wanted to be a landlord in the first place.
When you embrace the principle that no product is universally good or bad, you free yourself from hype and fear. You stop asking, “Is this product good?” and instead ask, “Is this product appropriate for my principles, my season of life, my risk tolerance, and my long-term design?” That is a very different conversation, a much healthier one.
Reflective Question: Which financial product have you labeled as “always good” or “always bad”? What assumptions might be hiding under that label?
Practical Lesson: The next time you hear a strong opinion about a financial product, pause and ask: “In what context might this be helpful? In what context might it be harmful?” This simple question keeps you grounded in discernment rather than slogans.
Better Questions, Better Outcomes: Rethinking How You Evaluate Choices
Most financial mistakes don’t start with bad math; they start with bad questions. “How much can I qualify for?” leads somewhere very different than “How much can I comfortably steward?” “What’s the maximum contribution I can make?” is not the same as “What structure best supports my long-term goals and tax awareness?” The quality of your questions shapes the quality of your outcomes.
Consider retirement accounts. A product-first question is, “Which account has the highest potential return?” A principle-first question is, “How do I balance tax awareness, access to capital, and long-term security?” From there, more refined questions emerge:
“What level of control do I want over my investments?”
“How important is liquidity versus locking up funds?”
“What tax environments do I expect now and later?”
The same applies to banking. Instead of asking, “Which bank pays the highest interest?” you might ask, “How do I design a banking system that supports my business cash flow, household stability, and opportunity fund?” That question invites you to think in terms of systems over shortcuts a core value at BDE Wealth rather than chasing small, isolated advantages that may not matter in the bigger picture.
Reflective Question: What is one financial area in your life where you’ve been asking narrow, product-focused questions? How could you reframe those questions around principles and long-term design?
Practical Lesson: Before any major financial decision, write down at least five questions that begin with “How will this…” (for example, “How will this affect my cash flow?” “How will this impact my ability to give?” “How will this interact with my business or tax situation?”). Bring those questions into any conversation with a professional.
Stewardship: The Lens That Changes Every Decision
At the heart of the BDE Wealth philosophy is a simple idea: stewardship before accumulation. Stewardship asks, “How am I caring for what has been entrusted to me?” rather than “How quickly can I get more?” This shift in posture changes how you view every financial product and strategy. You move from chasing outcomes to designing a life that reflects your values, responsibilities, and desired legacy.
Imagine two people buying real estate. One views property as a way to “get rich quick.” Their decisions may be driven by speculation, leverage, and fear of missing out. The other sees real estate as a tool to steward resources: providing housing, creating stable cash flow, and building something that can serve their family and community over time. They might buy fewer properties, but with more intention and resilience. The same product real estate operates in two entirely different systems because the underlying posture is different.
Stewardship also influences how you respond to risk. Instead of avoiding all risk or embracing reckless risk, a steward asks, “What risks are appropriate for my purpose and responsibilities?” That question can guide decisions about investments, business expansion, borrowing, and even when to say “enough” in a culture that constantly pushes for more.
Reflective Question: If you viewed every dollar, account, and asset in your life as something you are temporarily responsible for, not something you own forever, how might that change your decisions?
Practical Lesson: Before major financial commitments, ask: “Does this help me steward my time, relationships, health, and impact, not just my money?” If the answer is unclear, slow down and revisit your design.
Financial Education: Your Filter for Evaluating Products
Principles give you direction; education gives you discernment. Without a working understanding of how money, taxes, risk, and structures operate, it is difficult to evaluate whether a product truly serves your principles. This is why BDE Wealth emphasizes education before persuasion. The goal is not to push you toward a particular strategy, but to equip you to ask better questions and recognize when something does or does not fit your design.
For example, understanding the basics of how life insurance works protection, cash value, costs, guarantees, flexibility allows you to see beyond slogans. You can ask, “How does this policy interact with my other assets? What are the tradeoffs between liquidity, guarantees, and long-term cost?” Similarly, basic education about business entities helps you see why a certain structure might align with your risk profile, growth plans, and tax awareness rather than simply copying what a friend did.
Education does not mean becoming your own attorney, advisor, or accountant. It means building enough understanding to participate in the conversation, recognize red flags, and know when to seek specialized guidance. It is the difference between being a passenger and being the architect of your financial life. When you prioritize education, you naturally move toward systems over shortcuts and away from one-off decisions driven by emotion or marketing.
Reflective Question: In which area insurance, business structures, retirement accounts, banking, real estate, or investments do you feel the least informed? How has that lack of clarity impacted your confidence?
Practical Lesson: Choose one area of your finances to study over the next 90 days. Read educational articles, attend a workshop, or explore a course focused on understanding, not selling, so that future product decisions in that area are grounded in knowledge, not guesswork.
Intentional Planning: The Antidote to Emotional Decision-Making
Money decisions are rarely made in a vacuum. They are made after a market crash, during a move, in the middle of a health scare, or while scrolling through persuasive stories online. Without a clear plan, emotions easily take the driver’s seat. Fear says, “Sell everything.” Greed says, “Double down.” Envy says, “Do what they did.” A thoughtful plan, built on principles and education, acts as a stabilizing force when emotions run high.
Planning does not mean predicting every detail of the future. It means designing structures in advance so that when opportunities or challenges appear, you are not starting from zero. For example, deciding ahead of time how much of your income will be directed toward liquidity, long-term growth, giving, and debt reduction can reduce the temptation to react impulsively to every headline or sales pitch. Clarifying your investment philosophy before volatility hits can keep you from abandoning a sound approach at the worst possible moment.
Planning is also a form of stewardship. It respects your future self, your family, and your legacy by not leaving everything to chance. When your structures entities, accounts, protections, banking systems are designed thoughtfully, they support you in making patient, long-term decisions even when your emotions are loud. This is where structure before strategy becomes more than a phrase; it becomes a practical shield against reactionary choices.
Reflective Question: Think of a time when emotion drove a financial decision for you. If you had a clear written plan in place, how might that situation have unfolded differently?
Practical Lesson: Set aside time to write a simple “decision script” for future stressful moments. For example: “If markets drop by X%, I will review my plan before making changes,” or “If I’m presented with a new product, I will wait 48 hours and compare it against my principles and existing structures.” This small habit can prevent big mistakes.
Discovery Before Recommendations: A New Way to Engage with Advice
Too often, financial conversations jump straight to recommendations: “You should buy this,” “You need that,” “Everyone is doing this strategy.” The BDE Wealth approach reverses that sequence: discovery before recommendations. Discovery means taking the time to understand your story, values, responsibilities, fears, and hopes. It means mapping your current structures, entities, accounts, protections, debts, and assets before suggesting any new tools to add to the mix.
When discovery comes first, you are less vulnerable to persuasion tactics that rely on urgency or complexity. You are more likely to recognize when a recommendation is truly aligned with your principles and long-term design or when it is simply a product in search of a buyer. This is also where financial sovereignty begins: not in having every answer, but in being an active participant in the discovery process, rather than a passive recipient of sales pitches.
Reflective Question: When was the last time a financial professional spent more time asking about your values, responsibilities, and goals than talking about their products or strategies?
Practical Lesson: In your next financial conversation, notice the ratio of discovery to recommendation. If recommendations arrive before a deep understanding of your situation, consider slowing the conversation down or seeking a more educational, discovery-driven environment.
Conclusion: Stewardship, Sovereignty, and Intentional Wealth Design
Financial products will continue to evolve. New accounts, policies, funds, and strategies will appear, each promising some combination of security, growth, or tax advantage. But beneath the noise, the core invitation remains the same: Will you let your financial life be shaped by products or by principles?
When you choose principles first, you step into stewardship. You acknowledge that wealth is more than numbers; it includes time, relationships, knowledge, character, and impact. You recognize that your decisions today ripple into future generations. You begin to see financial products not as magic solutions, but as tools that either support or undermine the design you are building. This is the essence of intentional wealth design: aligning structures, strategies, and habits with a clear, values-driven blueprint for your life and legacy.
Sovereignty grows as you gain education, ask better questions, and insist on discovery before recommendations. You move away from fear-based marketing and toward truth over trends. You become less reactive to short-term emotions and more anchored in long-term thinking. You stop chasing shortcuts and start building systems that can serve you, your family, and your community for decades, not just quarters or news cycles.
At BDE Wealth, our role is not to tell you which product to choose, but to help you see the bigger picture: stewardship before accumulation, structure before strategy, education before persuasion, systems over shortcuts, discovery before recommendations, and long-term thinking over short-term emotion. Whether you are evaluating life insurance, business entities, retirement accounts, banking systems, real estate, or investments, the invitation is the same: start with principles, then choose products that honor them.
If you are ready to move from confusion to clarity and begin designing your wealth with intention, consider taking a next step in your education journey. Explore resources that deepen your understanding of money, structures, and legacy. Engage in conversations that prioritize discovery over sales. Whether that looks like a Legacy Fit Session, joining a learning community like Sovereignty Circle, or simply committing to a season of focused study, you are not just choosing new tools; you are choosing a new way of thinking about wealth itself.
Your financial life is being built, piece by piece, whether by design or by default. Let your next decision be guided not by the newest product, but by the enduring principles you want your life and legacy to stand on.