Life Insurance Is a Legacy Asset, Not Just a Safety Net
Wealth Design, Legacy Planning, Life Insurance Stewardship
Life Insurance Is a Legacy Asset, Not Just a Safety Net
Most people are introduced to life insurance as a simple “what if” tool—if something happens to you, your family receives money. That’s important, but it’s also incomplete. When you zoom out and think like a steward, life insurance stops being just a safety net and starts looking like one of the most powerful legacy assets a family or business can own.
From Safety Net to Stewardship Tool
At BDE Wealth, we view wealth through the lens of stewardship, sovereignty, structure, discernment, and legacy. Money is only one part of the equation. Your time, relationships, values, and decisions all play a role in the story you’re writing for your family and community.
In that context, life insurance is not just a product you buy and forget about. Properly designed, it becomes a strategic legacy asset—a structured pool of capital that can:
Provide immediate liquidity when your family or business needs it most
Protect surviving family members from financial chaos and rushed decisions
Support business continuity and keep teams, clients, and partners stable
Create opportunities for future generations that might not exist otherwise
Preserve wealth that could otherwise be eroded by taxes, debt, or forced asset sales
Life Insurance as a Legacy Asset, Not a One-Time Payout
When you hear “asset,” you might think of real estate, a business, or an investment portfolio. But a well-structured life insurance policy can sit right alongside those as a core legacy asset. Here’s why:
It’s contractual—the death benefit is not a hope; it’s a legal promise, assuming premiums are paid and the policy is in good standing.
It’s typically income-tax free to beneficiaries under current law, making it a highly efficient way to pass value.
It can be designed to support trusts, buy–sell agreements, and legacy plans, adding structure to your intentions.
Think of it as a funded promise to your future: “No matter when I pass, there will be capital available to continue the mission, care for the people I love, and protect what we’ve built.”
Liquidity: The Quiet Superpower of Life Insurance
One of the most overlooked benefits of life insurance is liquidity. When someone passes, bills don’t pause. Taxes, debts, legal fees, and everyday living expenses still need to be paid. Yet many assets—real estate, private businesses, retirement accounts—aren’t easily or quickly converted into cash without friction or loss.
A policy’s death benefit creates immediate, predictable liquidity at precisely the moment your family or business is under the most pressure. That liquidity can:
Prevent the fire sale of investments or property just to raise cash
Cover taxes and legal costs so heirs aren’t forced into debt or conflict
Provide a bridge of time for thoughtful, rather than rushed, decisions
Liquidity is about sovereignty. It gives your family and partners options, rather than forcing them into choices they may later regret.
Protecting Surviving Family Members Without Creating Dependency
Traditional life insurance conversations often stop at “replace your income.” That’s a start, but intentional families think more deeply. They ask: “What do I actually want this money to do for my spouse, children, or other dependents?”
Protection doesn’t mean creating lifelong dependence. It means giving your family the space and stability to grieve, reorient, and rebuild without panic. That might look like:
Paying off the mortgage so your spouse isn’t forced to move or downsize immediately
Funding a transition period for a stay-at-home parent to re-enter the workforce on their terms
Ensuring children can continue their education and activities without disruption
When aligned with your values and communicated clearly, life insurance becomes a tool for stability and dignity, not a lottery ticket or a source of confusion.
Supporting Business Continuity and the People Who Built It with You
For business owners, life insurance can be the difference between a business that dies with you and a business that outlives you. It’s not about “protecting the company” in the abstract; it’s about protecting your team, your clients, and your family’s relationship with the business you’ve built.
In a buy–sell agreement, life insurance can fund the purchase of your ownership by partners, preventing conflict and ensuring your family receives fair value without having to run the business.
For key employees, it can provide the capital needed to recruit leadership, stabilize operations, or pay down debt so the business can continue serving customers.
In this way, life insurance becomes part of your business continuity plan—a structured way to honor the people and systems that helped create your success while protecting your family’s interests.
Creating Opportunities for Future Generations
Legacy is not about handing the next generation a pile of money and hoping for the best. It’s about intentionally designing opportunities that align with your family’s values and vision. Life insurance can fund:
Education funds for children and grandchildren, paired with expectations around contribution, effort, or service
Seed capital for family members who want to start businesses or invest in real estate under clear guidelines
Family foundations or donor-advised funds that allow your heirs to practice generosity together
When integrated with trusts and a written legacy blueprint, the death benefit becomes a funding engine for the impact you want your family to have long after you’re gone—financially, relationally, and in the community.
Preserving Wealth That Might Otherwise Be Lost
Taxes, debt, and disorganization can quietly erode a lifetime of work. While life insurance is not a magic shield, it can be a powerful component of a wealth preservation strategy when coordinated with your estate plan, business structure, and tax strategy.
Some families use life insurance to:
Provide cash to pay estate or inheritance taxes, so assets don’t have to be sold under pressure
Equalize inheritances when one child is involved in the family business and others are not
Backstop charitable commitments or long-term care plans without draining other accounts
The goal is not to “beat the system,” but to act with discernment and structure so more of what you’ve created actually reaches the people and causes you care about.
Income Replacement vs. Legacy Strategy: Two Very Different Mindsets
Many people purchase life insurance with one simple calculation: “If I make X per year, how much coverage would replace that for a while?” That’s the income replacement mindset. It’s not wrong—but it’s limited.
Legacy-minded families and business owners take a different approach. They ask questions like:
“What roles do I play in my family and business, and how would those be funded or replaced?”
“What promises have I made—to my spouse, kids, partners, or community—and how will those be honored?”
“How can this policy support our long-term vision for education, business ownership, giving, and impact?”
That shift—from “How much do I need?” to “What am I designing?”—is the difference between buying a product and building a legacy system. It reflects the stewardship-focused philosophy shared by leaders like Garrett Gunderson: create value, design intentionally, and align money with your life, not the other way around.
Why Reviewing Your Coverage Is an Act of Stewardship
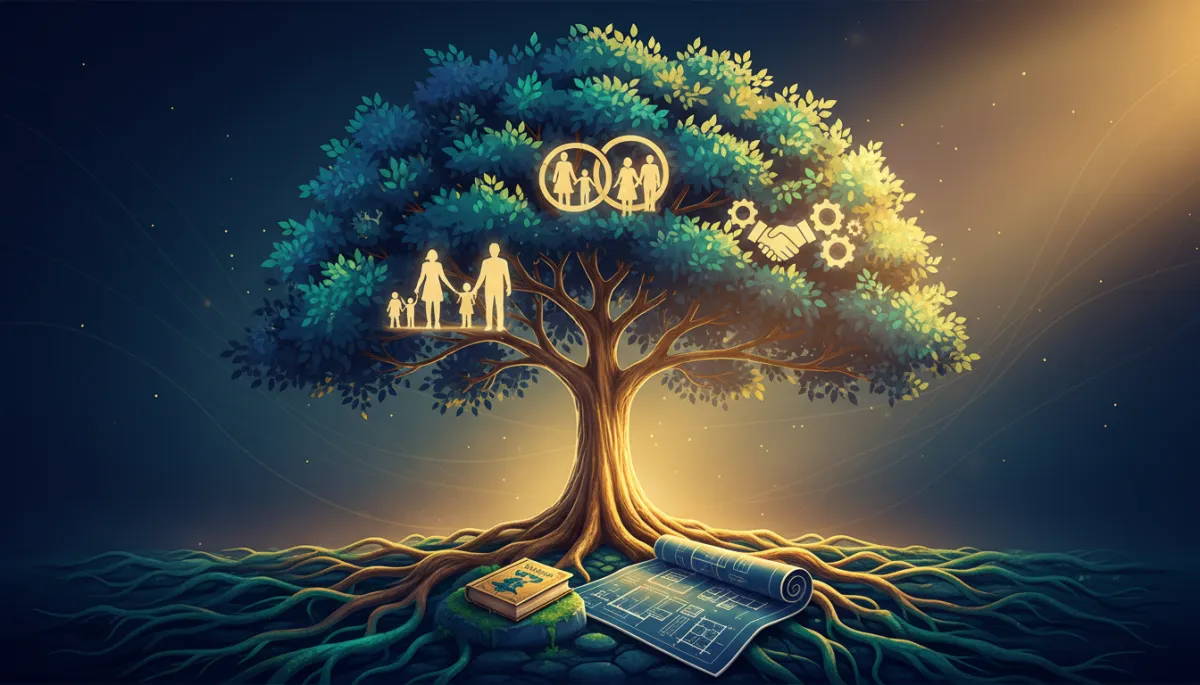
Life changes. Families grow. Businesses expand. Debts are paid off. New opportunities appear. Yet many people set up a policy once and never look at it again. From a stewardship perspective, that’s like planting a Tree of Life and never checking the soil, water, or roots.
Periodically reviewing your coverage is a practical way to honor your responsibilities. Consider revisiting your strategy when:
You get married, divorced, or welcome a new child or grandchild
Your income, debts, or assets change significantly
Your business grows, adds partners, or restructures ownership
You update your estate plan, trusts, or charitable goals
The goal of a review is not to chase trends or constantly switch products. It’s to make sure your life insurance still fits your current reality and long-term design—that it remains a living, aligned legacy asset rather than a forgotten line item.
Bringing It All Together: Designing Your Legacy with Intention
When you view life insurance through the lens of stewardship and sovereignty, it stops being about “having a policy” and starts being about designing a system. A system that:
Provides liquidity when your family or business needs it most
Protects surviving family members without creating dependency or drama
Supports business continuity and honors your partners and team
Creates opportunities for future generations to learn, build, and contribute
Preserves wealth that might otherwise be lost to taxes, debt, or disorganization
Life insurance is not the whole plan. It’s one important piece of a thoughtfully designed structure that includes your business entities, estate documents, tax strategy, education, and family conversations. But when used intentionally, it’s a piece that can quietly hold everything together at a critical moment—and empower the people you love to move forward with clarity instead of chaos.
Your Next Step: Is Your Life Insurance Truly a Legacy Asset?
You don’t need to become an expert overnight, and you don’t need to chase the latest financial fad. What you can do is take an honest look at your current coverage and ask: “Is this policy simply replacing income, or is it part of an intentional legacy strategy?”
If you’d like a structured, educational conversation about how life insurance fits into your broader wealth design, BDE Wealth offers a Legacy Fit Session™. This is not a sales pitch; it’s a guided review to help you see:
How your current policies align with your family, business, and legacy goals
Where there may be gaps, overlaps, or structural opportunities
Practical next steps to strengthen your overall legacy system with clarity and confidence
If you’re ready to explore whether your life insurance is truly functioning as a legacy asset—and how it can better support your stewardship, sovereignty, and long-term vision—you’re invited to schedule a Legacy Fit Session™ and take the next intentional step in your wealth journey.