Life Insurance Is About Living, Not Just Dying
Life Insurance, Stewardship, Legacy Planning, Financial Education
Life Insurance Is About Living, Not Just Dying
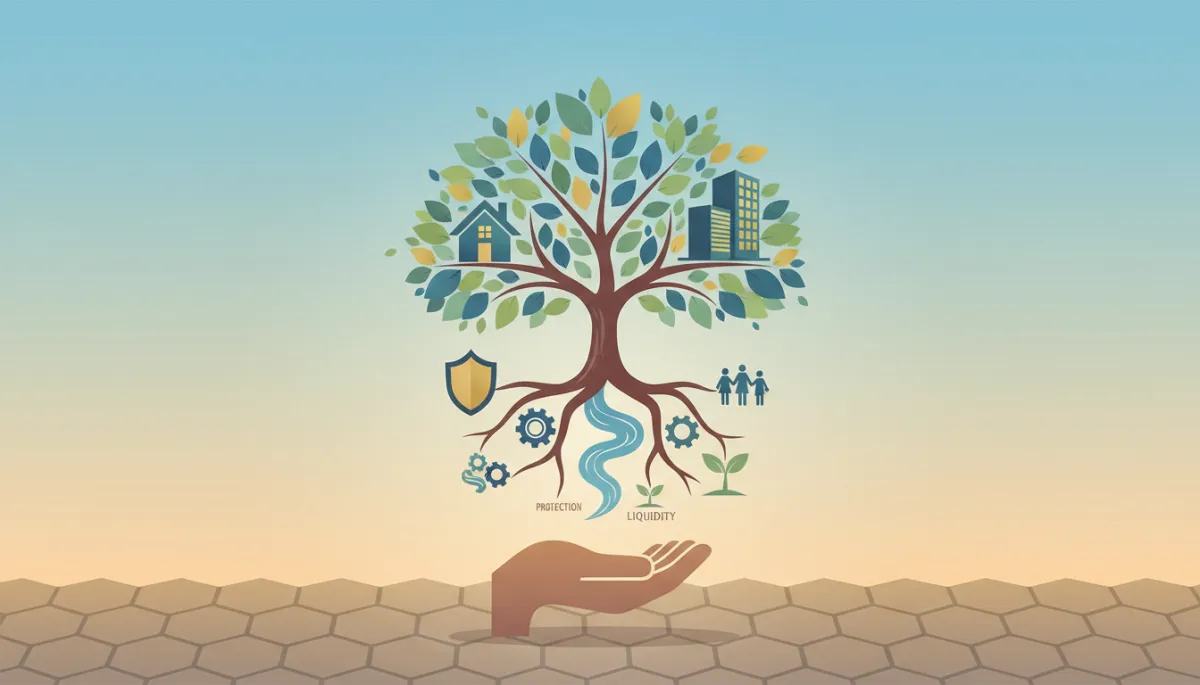
Life insurance is often introduced with a single question: “What happens if you die?” At BDE Wealth, we believe that is an incomplete way to think about such a powerful financial tool. Life insurance is not simply a contract that activates at death. When used with intention, it becomes part of a living design that supports your family, your business, your opportunities, and your legacy while you are very much alive.
Stewardship Before Accumulation: Why Life Insurance Starts with Purpose
At its core, life insurance is a stewardship decision, not a product decision. Stewardship asks a different set of questions than traditional financial marketing. Instead of “How big can this policy be?” stewardship asks, “What has been entrusted to me, and how am I called to manage it wisely for the people and purposes I care about most?”
When you view life insurance through the lens of stewardship, the death benefit becomes only one part of the conversation. You begin to consider how this tool can stabilize your finances, protect your family’s decisions, support your business, and create financial sovereignty the ability to make choices based on values and strategy, not pressure and fear. The question shifts from “How much coverage do I need if I die?” to “How can this tool help me live, lead, and give more intentionally while I am here?”
Reflective Question: If you viewed life insurance as a stewardship responsibility rather than a sales product, what would you want it to protect and make possible in your lifetime?
Practical Takeaway: Before looking at any numbers or illustrations, write down the people, responsibilities, and long-term purposes you believe you are called to steward. Let that list guide every future conversation about life insurance.
Structure Before Strategy: Where Life Insurance Fits in an Intentional Design
Many people encounter life insurance as a stand-alone purchase. A friend gets licensed. A colleague shares a “can’t-miss” illustration. A seminar promises tax-free income. Policies are often bought in isolation, separate from business structure, estate documents, cash flow planning, and long-term goals. At BDE Wealth, we teach structure before strategy. A tool is only as effective as the structure it serves and the design it supports.
Think of your financial life like a well-designed building. The foundation is your values and stewardship philosophy. The framing is your legal and financial structure: entities, accounts, agreements, and protections. Strategy is how you use each room. Life insurance is not the house; it is a structural support that can reinforce walls, stabilize the roof, and protect the people inside when storms arrive. Without a clear blueprint, even a well-built beam can end up in the wrong place, doing the wrong job, at the wrong cost.
Intentional wealth design asks, “What role should life insurance play for my family, my business, and my legacy?” It may serve as a liquidity source, a risk management tool, a way to equalize inheritances, or a means to preserve key assets from forced sale. Each role requires different structures, ownership, beneficiaries, funding methods, and coordination with other planning tools. The policy itself is not the design; it is one piece of a larger system.
Reflective Question: If your financial life were a building, where would life insurance sit- foundation, support beam, emergency exit, or something else? What structure around it would make it most effective?
Practical Takeaway: Before adjusting or purchasing a policy, map your current financial “structure”: entities, accounts, debts, assets, and legal documents. Ask a professional to show you where life insurance currently fits and where it should fit within that structure.
Financial Sovereignty: Using Life Insurance to Protect Choices, Not Just Income
Financial sovereignty is the ability to make decisions based on conviction and clarity rather than panic or pressure. Life insurance, when designed well, can be a quiet ally in maintaining that sovereignty. It does not replace your responsibility to earn, save, invest, and build. Instead, it supports those efforts by reducing the financial shock of life’s disruptions and by giving your family and your business more time to make thoughtful decisions when circumstances change.
Consider a family where one spouse is the primary earner and the other manages the home and children. Without life insurance, the death of the primary earner can force immediate, painful decisions: selling the home, changing schools, or rushing back into the workforce under duress. With a well-structured policy, the surviving spouse gains time and options. They can grieve without financial panic, maintain stability for the children, and choose work that aligns with their skills and values rather than whatever appears first. That is sovereignty in practice: the ability to choose, not just react.
Sovereignty also applies to business owners. A key person or owner’s death can trigger loans being called, partners scrambling for cash, or family members pressured to sell their interest quickly. Properly integrated life insurance can provide the liquidity needed to buy out shares, pay obligations, and preserve the business until a thoughtful transition can occur. The policy is not just about death; it is about keeping decisions in the hands of people who know the mission and values of the enterprise.
Reflective Question: In a major life disruption, what choices would you want your family or business partners to have? Which of those choices would require cash, time, or liquidity to be possible?
Practical Takeaway: List three decisions you would want your family or business to be able to make freely if something happened to you. Use that list as a guide when considering the size and structure of any life insurance coverage.
Family Financial Security: Creating Stability, Not Dependence
When most people think of family financial security, they picture replacing income after a death. While income replacement is important, it is only one layer of protection. True security is about stability, continuity, and the ability to continue living according to shared values even when circumstances change. Life insurance, used wisely, can underwrite that stability without creating unhealthy dependence or entitlement.
Imagine a family with young children. Their goals include providing a stable home, consistent education, and the opportunity for the children to develop their gifts. If a parent dies, the question is not only, “Can we pay the bills?” but also, “Can we keep our commitments to these children?” Life insurance can be structured to pay off a mortgage, fund education accounts, and provide a cushion for ongoing living expenses. This reduces financial stress in an already difficult season and allows the surviving parent to focus on parenting and healing rather than scrambling for income overnight.
For blended families, multi-generational households, or families caring for aging parents, thoughtful coverage can prevent conflict and confusion. Clear beneficiary designations, coordinated with estate documents, help ensure that resources flow where they are intended, not where default laws assume they should. Here, life insurance is less about a number and more about clarity: who needs what, when, and for how long to remain secure and supported.

Clear planning turns life insurance from a vague product into a practical family safety net.
Reflective Question: If you were not here tomorrow, what specific commitments to your spouse, children, or dependents would you want to see honored over the next 5, 10, or 20 years?
Practical Takeaway: Translate vague goals (“take care of my family”) into specific commitments (housing, education, caregiving, debt payoff). Use those commitments as the framework for determining how life insurance can support real-life needs.
Business Continuity: Protecting People, Partnerships, and Promises
For business owners and entrepreneurs, life insurance is often a crucial piece of business continuity. A business is more than revenue; it is a collection of relationships, promises, and responsibilities. Employees, clients, vendors, lenders, and partners all rely on the stability of the enterprise. When a key person dies, the business can either falter under pressure or remain steady because planning and protection were in place long before the crisis.
Consider a small company with two partners. One handles operations; the other handles sales and relationships. If one partner dies, the surviving partner may be willing to continue the business, but the deceased partner’s family may need cash, not shares in a private company. A well-designed buy-sell agreement, funded by life insurance, can provide the liquidity for the surviving partner to buy out the deceased partner’s interest at a predetermined value. The family receives financial support, and the business continues without forced liquidation or conflict. The policy did not exist “because someone might die”; it existed to honor commitments and protect people on both sides of the agreement.
Life insurance can also support the recruitment and retention of key employees, secure loans, or provide a pool of funds for leadership transition. When integrated into the business’s overall structure, it becomes part of a thoughtful succession plan rather than an afterthought. The goal is not to accumulate policies but to align coverage with real risks, promises, and long-term plans for the enterprise.
Reflective Question: If a key partner, owner, or leader in your business were gone tomorrow, who would be financially exposed, and what agreements or obligations would suddenly become urgent?
Practical Takeaway: Review your operating agreements, loan documents, and succession plans. Identify where life insurance could provide the cash needed to keep promises, protect families, and preserve the business during a transition.
Estate Liquidity and Wealth Transfer: Preserving Assets Instead of Selling Them
Many families work hard to build businesses, real estate portfolios, or investment accounts, only to see those assets strained or sold under pressure after a death. Taxes, debts, legal fees, and settlement costs can create a sudden demand for cash. Without planning, heirs may have to sell appreciated assets quickly often at unfavorable prices just to meet obligations. Here, life insurance can play a quiet but powerful role in estate liquidity and wealth transfer planning.
Picture a family that owns several rental properties and a closely held business. Much of their wealth is tied up in illiquid assets that produce income but are not easily sold. At death, estate taxes or debts may come due. Without liquidity, beneficiaries may have to sell properties or pieces of the business quickly, disrupting tenants, staff, and long-term plans. A properly structured life insurance policy can provide the cash needed to pay obligations while allowing the family to keep the underlying assets intact. Instead of being forced sellers, they become patient stewards, able to make decisions based on strategy rather than urgency.
Life insurance can also help equalize inheritances when some heirs are involved in the family business or real estate, and others are not. Rather than dividing ownership in ways that create conflict, parents can leave operating assets to those active in the enterprise and use insurance proceeds to provide fair value to others. In this way, life insurance supports both family harmony and operational continuity a critical element of legacy stewardship.
Reflective Question: If your estate needed cash within nine months of your death, where would it come from? Which assets would you least want your heirs to be forced to sell quickly?
Practical Takeaway: Work with your advisory team to estimate potential estate costs and liquidity needs. Evaluate whether life insurance could provide the cash required to preserve key assets and reduce stress on your heirs.
Long-Term Planning and Risk Management: Preparing for the Inevitable and the Unexpected
Stewardship recognizes that life is uncertain, but responsibility is not. We cannot predict every event, but we can prepare for categories of risk. Long-term planning and risk management are about building a system that absorbs shocks without collapsing. Life insurance is one component of that system, working alongside emergency reserves, disability coverage, business structures, and legal documents to create resilience over decades, not just years.
In long-term planning, life insurance can help address predictable realities: aging, succession, and eventual death. It can also provide a backstop for less predictable events, such as sudden illness, business disruption, or economic downturns that coincide with a death. The goal is not to insure everything but to identify which risks would cause the greatest harm to people, promises, and long-term goals if left unaddressed. From there, you can decide where life insurance is the right tool and where other strategies are more appropriate.
A helpful analogy is a well-designed ship. The hull, compartments, and pumps are built to handle storms and leaks. Life insurance is not the ship; it is one of the pumps that keeps water from overwhelming the vessel when a specific compartment is breached. You still need a strong hull (sound finances), a skilled crew (your advisors and family), and a clear destination (your values and legacy goals). But without pumps, even a well-built ship can be lost when water rises faster than you can respond.
Reflective Question: Which financial risks death, disability, business disruption, tax changes would most threaten your long-term plans if they occurred at the wrong time?
Practical Takeaway: List your top three financial risks and rank them by potential impact. Discuss with a professional which risks are best managed through insurance and which require structural or behavioral changes.
Financial Flexibility: Creating Options and Reducing Stress During Life’s Transitions
A central theme in BDE Wealth’s philosophy is that money should expand your ability to live intentionally, not trap you in rigid patterns. Financial flexibility is the capacity to pivot when circumstances, opportunities, or callings change. While life insurance is not a savings account or investment strategy, certain designs can support flexibility by providing liquidity, stabilizing other assets, or reducing the need to liquidate investments at inopportune times when a death occurs.
For example, a family might hold long-term investments in real estate or privately held companies. If a death coincides with a market decline or a temporary downturn in rental income, selling those assets quickly could lock in losses. A well-structured life insurance policy can provide cash to cover expenses, debts, or tax obligations, allowing the family to hold or reposition assets intentionally rather than reactively. The value is not just in the death benefit number, but in the options it preserves at critical moments.
Flexibility also shows up in how life insurance interacts with charitable goals, multi-generational planning, and business transitions. Policies can be coordinated with trusts, gifting strategies, or buyout arrangements to ensure that resources are available when they are most needed, not just when they are easiest to fund. Again, the focus is on design and coordination, not on chasing illustrations or promises of extraordinary returns.
Reflective Question: In a major life transition, what options would you most want to preserve keeping a property, maintaining a business, supporting a cause, or providing for family?
Practical Takeaway: Identify which assets or commitments you would be most reluctant to sacrifice in a crisis. Evaluate whether life insurance could provide the liquidity needed to protect those priorities.
Legacy Stewardship: Passing Wisdom Alongside Wealth
At BDE Wealth, we talk often about legacy stewardship the responsibility not only to leave resources, but also to pass on the understanding and values required to manage those resources well. Life insurance can fund a legacy, but it cannot define one. A large death benefit without education, clarity, and structure can create confusion, conflict, or even harm. A thoughtfully integrated policy, combined with teaching and communication, can become a tool that supports the next generation rather than overwhelming them.
Legacy-minded families often use life insurance to create a financial “bridge” for the next generation, providing resources for education, business ventures, or charitable work while preserving core assets for long-term growth. Some families design policies to support family foundations, donor-advised funds, or mission-driven projects that reflect their deepest convictions. Others use coverage to equalize inheritances, protect special-needs family members, or ensure that a surviving spouse remains financially secure without derailing long-term plans for children and grandchildren.
The key is education before persuasion. Heirs should understand why policies exist, what they are intended to support, and how they fit within the broader family design. Conversations about stewardship, responsibility, and decision-making are just as important as beneficiary forms and policy values. Legacy is not merely what you leave behind; it is what you build into the people who will follow you.
Reflective Question: If your heirs received a significant life insurance benefit tomorrow, what guidance, structure, or education would they need to manage it wisely and in alignment with your values?
Practical Takeaway: Begin documenting your financial philosophy, core values, and hopes for future generations. Consider how your life insurance design can reinforce those priorities rather than simply increase the size of an inheritance.
Evaluating Life Insurance Through the Lens of Stewardship, Not Sales
With so many product types, riders, and illustrations available, it is easy to get lost in technical comparisons and sales language. BDE Wealth’s approach is different: intentional design before product selection. Every financial tool should be evaluated based on the role it plays within an overall stewardship strategy, not on fear, commissions, or glossy projections. The “best” policy is the one that faithfully serves its intended purpose within a clear structure and a thoughtful plan.
Instead of asking, “Which policy type is best?” consider questions such as:
What specific risk or responsibility is this policy designed to address?
How does this coverage interact with my business structure, estate plan, and other protections?
Who needs clarity about this policy’s purpose so it can be used wisely when needed?
Does this design support long-term flexibility, or does it create unnecessary pressure on my cash flow?
When you start with why, the how becomes clearer and less emotional. Product illustrations become tools for testing design assumptions, not drivers of decision-making. Advisors become partners in stewardship, not salespeople pushing features. The conversation shifts from “What can this policy do?” to “How can this policy help me live and lead more intentionally, protect what matters most, and support a long-term legacy?”
Reflective Question: When you think about your existing or potential life insurance, are you more focused on illustrations and features, or on the specific stewardship roles you want it to play?
Practical Takeaway: For each policy you own or are considering, write a one-sentence purpose statement: “This policy exists to…” If you cannot complete that sentence clearly, pause before making changes or commitments.
Life Insurance as One Component of a Larger Stewardship Strategy
When you put all of these pieces together stewardship, structure, financial sovereignty, intentional wealth design, education, and long-term legacy a clear picture emerges. Life insurance is not the hero of your financial story, nor is it a villain to be avoided. It is one tool within a broader system designed to protect people, preserve options, and support wise decisions over time. Used well, it can:
Strengthen family financial security by stabilizing housing, education, and caregiving commitments.
Support business continuity by funding buyouts, honoring agreements, and preserving jobs.
Provide estate liquidity so heirs are not forced to sell meaningful assets under pressure.
Facilitate thoughtful wealth transfer that aligns inheritances with involvement, responsibility, and calling.
Enhance long-term planning and risk management by addressing specific vulnerabilities in your design.
Increase financial flexibility by providing liquidity at critical moments, reducing stress and rushed decisions.
Strengthen legacy stewardship by resourcing the values, missions, and relationships you care most about.
None of these outcomes happen automatically. They require clarity, coordination, and ongoing education. But when life insurance is integrated into a broader stewardship strategy, it becomes less about death and more about living: living with peace of mind, with aligned structures, and with the freedom to focus on what truly matters rather than constant financial uncertainty.
Reflective Question: Looking at your entire financial picture, where is life insurance currently serving a clear, intentional role and where is it missing, underused, or misunderstood?
Practical Takeaway: Treat your life insurance review as part of a broader stewardship audit. Examine how each policy connects to family, business, estate, and legacy goals rather than evaluating it in isolation.
Moving Forward: Designing a Life-Centered Approach to Protection and Legacy
Life insurance is about living, not just dying. It is about the lives you are responsible for, the businesses you have built, the opportunities you want to preserve, and the values you hope will outlast you. When approached through the lens of stewardship, sovereignty, and intentional design, it becomes a quiet but powerful ally in creating peace of mind and long-term impact. The goal is not to collect policies, but to design a system in which each tool, including insurance included has a clear purpose and a defined place.
As you think about your next steps, consider shifting your questions from “How much coverage should I buy?” to deeper, more foundational questions:
What people, responsibilities, and missions am I called to steward?
What legal, financial, and relational structures do I need to support that stewardship?
Where does life insurance appropriately fit within that design to protect, stabilize, and resource what matters most?
At BDE Wealth, our role is to help you see the whole picture: your family, your business, your risks, your opportunities, and your legacy, and then align tools, structures, and strategies accordingly. We do not lead with products. We lead with stewardship, education, and intentional design so that every decision, including life insurance, serves a clear and meaningful purpose.
If you are ready to think more intentionally about protecting the people, businesses, opportunities, and values that matter most to you, we invite you to explore how a comprehensive stewardship approach can work in your situation. A Legacy Fit Session™ is a focused conversation designed to help you understand how financial stewardship, business structure, risk management, and long-term planning fit together within a personalized wealth design. It is an educational step, not a sales presentation, and it is built to give you clarity so you can make informed, confident decisions.
To schedule your Legacy Fit Session™ and begin aligning your life insurance and broader financial strategy with your deepest values and long-term legacy, visit this link.