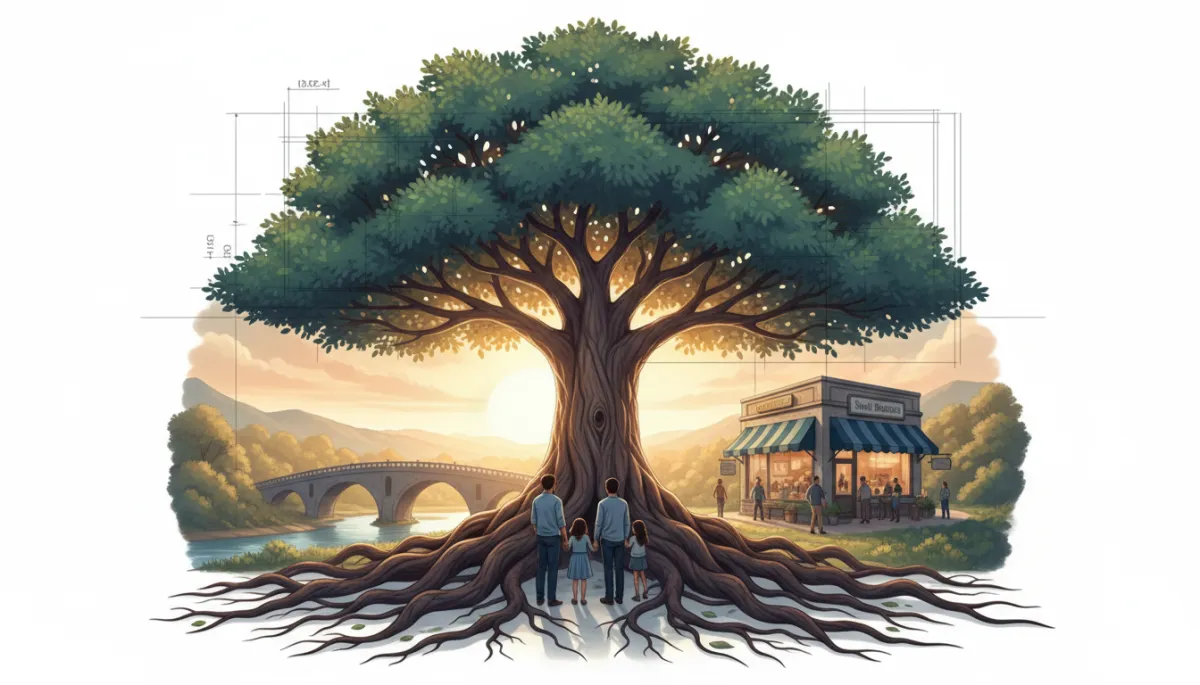
Premium editorial illustration of the Tree of Life sheltering a family and thriving business, connected by a bridge symbolizing continuity, stewardship, protection, and long-term legacy planning.
Financial Stewardship, Life Insurance, Legacy Planning, Business Continuity
Life Insurance Protects More Than Income
If your paycheck stopped tomorrow, what would actually be at risk—the income itself, or the people, promises, and plans that income was quietly holding together?
Seeing Life Insurance Like an Engineer: The Hidden Foundation of a Bridge
As a senior software engineer, I naturally think in systems, dependencies, and failure modes. When I look at life insurance, I don’t see a product. I see infrastructure—like the foundation of a bridge. Drivers rarely think about the concrete pillars underwater. They expect the bridge to hold every time they cross. But if that unseen foundation fails, everything on top is suddenly at risk: people, vehicles, cargo, schedules, and plans on both sides of the river.
Life insurance, when designed intentionally, plays a similar role. It’s the structural support beneath your family’s life, your business, and your long-term plans. You don’t buy it because you expect something bad to happen tomorrow. You put it in place because you understand stewardship: protecting what has been built, and what is still being built, from the kinds of shocks you can’t schedule on a calendar or log in an app.
💡 Stewardship Lens: At BDE Wealth, we talk about stewardship before accumulation and protection before reaction. Life insurance sits squarely in that category. It’s not about fear; it’s about structure.
Life Insurance’s True Purpose: Protecting People, Not Just Paychecks
Many people are told, “Life insurance replaces your income.” That’s technically true, but it’s incomplete—like saying a server “just runs code.” In reality, that server protects uptime, user trust, business operations, and reputation. Income is the data stream; people and responsibilities are the system relying on it. The deeper truth is this: life insurance is about protecting people, not just paychecks.
It protects families from being forced into panic decisions—selling a home, changing schools, or taking on crippling debt—right after a loss.
It protects business partners and employees from the chaos that can follow the loss of a key owner or leader.
It protects relationships and opportunities by giving people time to grieve and think clearly, instead of being shoved into survival mode.
When we strip life insurance down to “income replacement,” we miss what BDE Wealth emphasizes: stewardship, sovereignty, and intentional design. It’s not just about keeping money flowing. It’s about preserving the values and vision that income was supporting—education for kids, stability for a spouse, commitments to a team, generosity to a community, or the continuation of a business you’ve poured years into building.
Continuity: Keeping the System Running When the Architect Is Gone
In software, a well-designed system keeps running even if the original architect leaves the company. There are docs, tests, backups, and infrastructure that create continuity. Without that, a key departure can stall releases, break features, and hurt customers. Life works similarly. You are the “lead engineer” of many roles at once—provider, parent, partner, owner, leader, mentor. If you’re suddenly removed from the system, what keeps everything from crashing?
Life insurance is one of the core tools for continuity. It gives your family and business the resources to:
Maintain living standards while new income sources are created or adjusted.
Keep a business operating while a successor steps in, a sale is negotiated, or a transition plan is executed.
Avoid fire-sale decisions—rushed real estate sales, forced liquidation of investments, or taking on high-interest debt.
Reflective question: If you were removed from your family or business “system” overnight, what would break first—and how quickly?
Business Succession: Protecting the Team, Not Just the Balance Sheet
For business owners, life insurance is often the quiet engine under a well-thought-out succession plan. Think of a small software firm with two partners. One writes most of the critical infrastructure. The other leads sales and client relationships. If one partner dies unexpectedly, the business doesn’t just lose a salary. It loses specialized knowledge, trust, and momentum. Without a plan, surviving partners and families are left to improvise under pressure.
A stewardship-based approach uses life insurance to:
Fund buy-sell agreements, so surviving partners can buy the deceased partner’s shares at a fair value without draining business cash.
Provide key person protection, giving the company time and resources to recruit, train, or restructure around the loss of a key leader.
Protect employees and clients from abrupt shutdowns or chaotic transitions.
This is what BDE Wealth means by systems over shortcuts. A business succession strategy supported by life insurance is a system: documented, funded, and aligned with your values. It’s not just “having a policy.” It’s designing continuity for the people who depend on the business—employees, clients, vendors, and families.
Why Liquidity Matters Most When Life Is Least Predictable
Engineers know that when a system fails, the first priority is stabilization. In life, that often means liquidity—cash that shows up quickly, without needing a loan approval or a market to cooperate. During a crisis, liquidity buys the most valuable resource of all: time to think clearly.
Life insurance is one of the few tools that can deliver large, tax-aware, liquid capital exactly when it’s needed most. That liquidity can:
Cover immediate expenses—funeral costs, medical bills, travel for family—without swiping credit cards or selling assets at a discount.
Pay down or pay off key debts: mortgages, business loans, or personal guarantees that could threaten the family or company.
Provide a runway for a spouse or business partner to regroup, re-skill, or restructure without being forced into immediate, emotionally driven decisions.
Education before persuasion: Understanding the role of liquidity helps you see life insurance not as a bet on death, but as a certainty tool in uncertain times.
From “Buying a Policy” to Designing a Protection Strategy
In tech terms, buying a life insurance policy without a strategy is like spinning up a random server in the cloud with no architecture diagram, no monitoring, and no integration plan. It exists, but it’s not really part of your system. It might help, or it might just be an unnecessary cost. The difference between buying a policy and creating a protection strategy is intentional design.
A protection strategy asks questions like:
Who, specifically, am I protecting—spouse, children, parents, business partners, employees, or a combination?
What responsibilities do I carry that would still exist if I were gone—mortgages, tuition, payroll, contracts, promises?
What opportunities or long-term plans (education, business expansion, charitable giving) do I want to protect from disruption?
How does this protection integrate with my other structures—trusts, entities, savings, investments, and business agreements?
BDE Wealth’s philosophy—planning before emotional decisions—fits perfectly here. The goal isn’t to be sold a policy in a 30‑minute call. It’s to design a protection system that matches your life, your responsibilities, and your legacy goals. That may include life insurance, but it always starts with clarity.
A Simple “Protection Map” in Pseudocode
To think about this like an engineer, imagine a small script that maps responsibilities to protection tools. This isn’t financial advice—it’s a mental model:
responsibilities = [
    "family housing and lifestyle",
    "children's education",
    "business payroll and operations",
    "personal guarantees on loans",
    "long-term giving goals"
]

protection_tools = {
    "cash_reserves": [],
    "insurance": [],
    "legal_structures": [],
    "business_agreements": []
}

for item in responsibilities:
    if item in ["family housing and lifestyle", "children's education"]:
        protection_tools["insurance"].append(item)
    elif item in ["business payroll and operations", "personal guarantees on loans"]:
        protection_tools["insurance"].append(item)
        protection_tools["business_agreements"].append(item)
    else:
        protection_tools["legal_structures"].append(item)

print("Mapped protection strategy:")
for tool, covered_items in protection_tools.items():
    print(f"- {tool}: {covered_items}")
In real life, this “mapping” is part of what an intentional Legacy Fit Session™ explores: what exists, what’s at risk, and which structures—including life insurance—can support those responsibilities.
Stewardship: Protecting What Has Been Built (and What’s Still Growing)
Stewardship is one of BDE Wealth’s core values. It means recognizing that what you’ve built—your income, business, relationships, skills, and reputation—is not just for you. Others now depend on it. In engineering terms, you’ve moved from “side project” to “production system.” There are users on the other end of your decisions.
Stewardship-driven protection asks:
How do I protect the people who rely on what I’ve built—my family, my team, my clients?
How do I protect the structure itself—my business, my assets, my long-term plans—from being dismantled by an unexpected loss?
How do I preserve the values and vision that guided these decisions in the first place?
Life insurance, in this context, becomes less about “What’s my death benefit?” and more about “What story continues if I’m not here?” It’s one of the tools that lets your values—education, generosity, responsibility, sovereignty—keep flowing to the next generation, even if your physical presence doesn’t.
Fitting Life Insurance into an Intentional Wealth and Legacy Plan
Wealth, in the BDE Wealth framework, is more than money. It includes time, relationships, knowledge, character, and impact. An intentional wealth and legacy plan looks at all of those layers and asks, “How do we design this so it lasts?” Life insurance is not the star of that plan—but it is often a critical support beam in the structure.
Think in Layers, Not Products
One way to approach this—especially if you enjoy systems thinking—is to imagine your wealth and legacy as layered architecture:
layers = [
    "Core Values and Vision",
    "Family and Relationship Priorities",
    "Business and Career Structures",
    "Legal and Tax Frameworks",
    "Protection and Risk Management",
    "Growth and Investment Strategies"
]

for index, layer in enumerate(layers, start=1):
    print(f"{index}. {layer}")
Notice that Protection and Risk Management sits under growth and investment. That’s intentional. Stewardship says: protect the system before you optimize it. Life insurance typically lives in that protection layer, alongside emergency reserves, legal structures, and risk controls. Its role is to make sure the other layers—your family priorities, your business, your values—don’t collapse if something happens to you.
Preserving Values and Vision, Not Just Assets
Money alone doesn’t carry your values. But it does fund the environments where those values are lived out. If you value education, life insurance can help ensure your children still have the option to pursue it. If you value stability and presence, it can keep your spouse from working two jobs just to survive. If you value generosity, it can provide resources for causes you care about long after you’re gone.
“Legacy is not what you leave to people. It’s what you leave in them—and what you’ve equipped them to carry forward.”
Life insurance, used wisely, supports that kind of legacy by keeping options open and pressure down when life is at its hardest. It’s part of how you protect your family’s future as an act of responsibility, not fear.
Protecting a Family’s Future: An Act of Responsibility, Not Anxiety
Many people avoid life insurance conversations because they feel morbid or fear-based. But from a stewardship perspective, protecting your family’s future is one of the most grounded, responsible actions you can take. It’s similar to writing clean, well-documented code with tests: you don’t do it because you expect everything to break tomorrow. You do it because you respect the people who will maintain and use the system after you.
When you protect your family with an intentional life insurance strategy, you are essentially saying:
“I refuse to leave you with chaos if something happens to me.”
“I’ve thought beyond my own lifespan about your stability and opportunities.”
“I am willing to trade a small portion of today’s comfort for long-term protection of the people I love.”
Responsibility before fear: BDE Wealth’s approach is to educate you so that decisions about protection come from clarity and conviction, not pressure or panic.
The Bridge Analogy Revisited: Behind-the-Scenes Support for a Long Journey
Let’s come back to the bridge. Picture your life’s journey as a long road that crosses several deep valleys—career changes, raising children, starting or selling a business, caring for aging parents, and eventually, transferring your legacy. Each valley requires a bridge. You design the visible parts—your job, your company, your investments, your family routines. But underneath all of that is the foundation: the unseen structure that allows everyone to cross safely, even if the original builder is no longer there to supervise.
Life insurance, when aligned with a thoughtful plan, is like those deep concrete pillars anchored into the bedrock. It doesn’t get applause. It’s not glamorous. But it holds the weight of:
Families continuing to live, learn, and grow without being uprooted by financial shock.
Businesses transitioning leadership without collapsing under debt, confusion, or conflict.
Opportunities and responsibilities being honored instead of abandoned—educational paths, commitments to employees, or promises to partners.
You don’t design a bridge foundation because you’re obsessed with collapse. You design it because you respect the journey and those who will cross after you. That’s the heart of stewardship-based protection.
Practical Takeaways: Questions to Debug Your Protection Plan
To bring this down to earth, here are some calm, reflective questions you can ask—like running a diagnostic on your current system:
People Check: Who are the specific people my current life supports financially, emotionally, or structurally? How would their day-to-day life change if I were gone?
Responsibility Map: What debts, obligations, or commitments am I responsible for—personally or as a business owner—that would remain after me?
Continuity Test: Could my family or business function for 6–12 months without my income or leadership, without panic decisions?
Liquidity Reality: If something happened tonight, where would immediate cash come from—and what would we be forced to sell or borrow against?
Legacy Alignment: Is any existing life insurance I have actually connected to a broader plan for my family, business, and legacy—or is it just a line item on my bank statement?
These aren’t questions to scare you. They’re questions to clarify where your current “bridge” is strong and where the foundations might need reinforcement. Education before persuasion. Clarity before commitment.
Life Insurance’s Greatest Purpose: Protecting What Matters While You’re Still Here
When you zoom out, you start to see that life insurance is not just about preparing for death. Its greatest purpose is protecting the people, opportunities, and legacy you care about while you’re living. Knowing that your family, your business, and your long-term plans are structurally supported changes how you show up today. It can give you:
More confidence to grow your business or career, because you’ve handled the “what if” questions.
More peace in your relationships, because you’re not silently carrying all the risk alone.
More freedom to design your legacy with intention, knowing the bridge you’re building has a solid foundation.
That’s the heart of the BDE Wealth approach: legacy before lifestyle, systems over shortcuts, and stewardship over hype. Life insurance is not the whole story, but when aligned with your values and structures, it becomes a powerful chapter in how you protect and extend what matters most.
Your Next Step: Explore How Protection Fits Your Intentional Wealth Strategy
If you’re a family, business owner, professional, entrepreneur, or simply someone who cares about stewardship and legacy, the next step isn’t to rush out and “buy more insurance.” The next step is to understand how protection fits into your overall design—your entities, taxes, business, investments, and long-term goals.
A Legacy Fit Session™ with BDE Wealth is an educational, conversation-driven experience. It’s about mapping your current structures, clarifying your responsibilities, and exploring where tools like life insurance can support your people, your opportunities, and your long-term vision. No hype. No shortcuts. Just clarity and stewardship-focused guidance.
If you’re ready to move from “I think we’re covered” to “I know our foundation is strong,” you’re ready for that conversation. 👉 Schedule Your Legacy Fit Session™